
Bridging Finance is used on occasions where you have found your next home, but haven't yet sold your own home.
A bridging lender will take a mortgage over your existing home and the new home to allow you to complete your home purchase. Once your existing home is sold, some or all of the loan clears. Any remaining loan on the new home is then converted to a normal home loan.
Bridging lenders will allow a loan term of up to 12 months for your bridging loan. Some bridging lenders will require that you make interest only repayments during the bridging period. If you have enough equity in your home, some lenders will allow you to capitalise the interest on your bridging loan (meaning the interest is added to your loan balance each month).
Bridging does allow you to secure the home you really want, which is a good thing. But there a risks….
If you are weighing up bridging finance to get into your next home, we will be glad to help with assessing your options to help arrive at an informed decision.
If you're looking to buy a home in Queensland, Call Bribie Island Lending to talk through this option today.
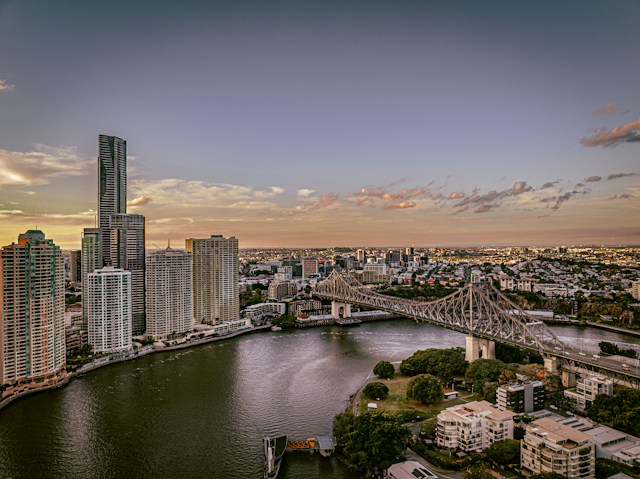
We are based on the beautiful Queensland coast, between the Sunshine Coast & Brisbane and we offer a complimentary home loan broking service.
Make an appointment today for an obligation-free chat, to talk about what you need and how we can help.
*This article is general information only and does not constitute financial advice. Your personal circumstances will need to be assessed before any product or proposal is recommended. Mark Hind is an Authorised Credit Representative (ACR 519951) of Outsource Finance Pty Ltd, Australian Credit Licence 384324.
A construction loan releases money in stages as your home is built, so repayments start small and grow, and understanding contracts, variations and extra costs before you sign helps keep the build on track.
With rates rising in 2026, fixed, variable and split loans each come with trade-offs in certainty, flexibility and cost, so the right choice depends on how you live and spend, not on guessing where rates go next.
Queensland first home buyers can currently draw on the federal 5% Deposit Scheme, a $30,000 grant for new homes and stamp duty concessions, but each has its own rules, and knowing how they fit together before you buy can make a real difference.
Whether you're just starting to explore your options or ready to move Mark and the team are here to help. Get in touch for a no-obligation chat and find out what's possible for your situation.


